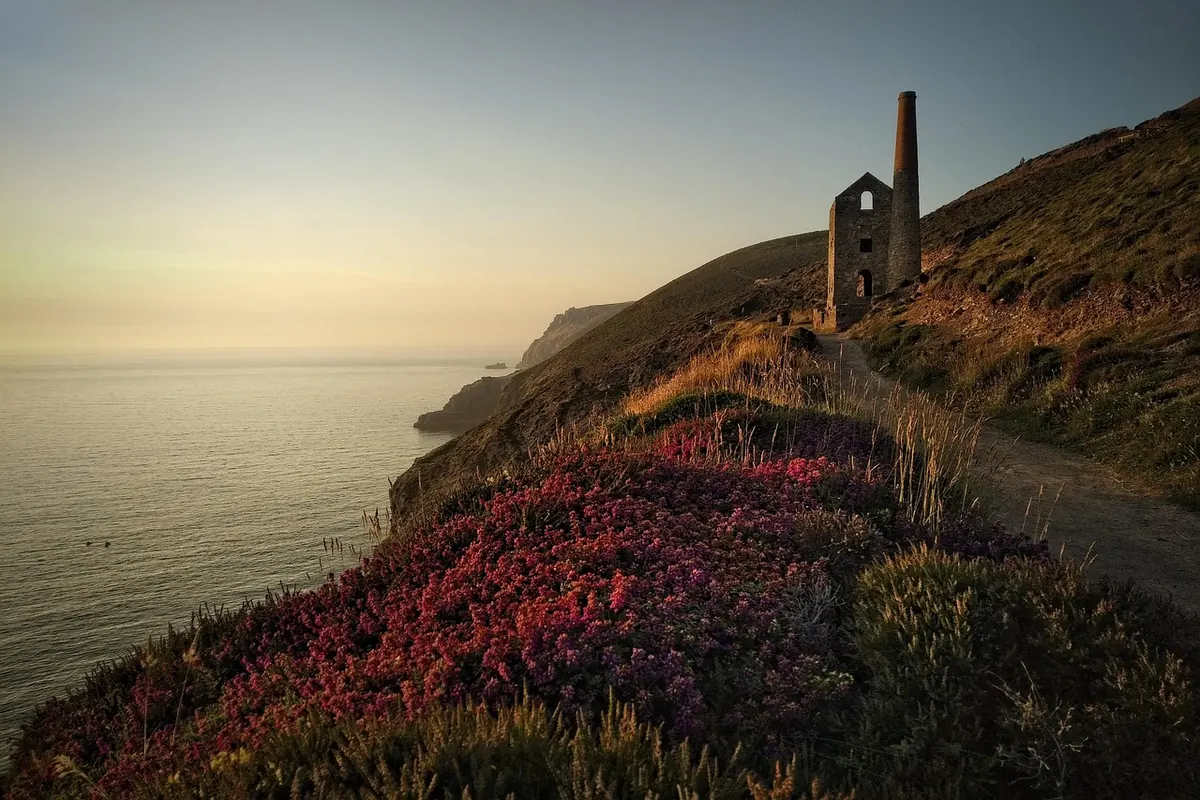
Cornwall was mining copper at industrial scale long before anyone needed a strategy to justify it. Between the eighteenth century and the 1880s, the Camborne, Redruth and Gwennap districts sent copper ore to smelters in South Wales and beyond, until cheaper ore from overseas shut the workings one by one. Deeper tin mining carried on for another century, but the copper was largely forgotten.
Now the same ground is being drilled again. Tin, lithium and copper are all in play, and copper's addition to the UK's critical minerals list in 2023 has given the county's prospects a different kind of attention — less nostalgic, more strategic.
The geology never went away
Cornwall's mineralisation comes from a granite mass that intruded the surrounding slate and baked it, pushing hot, metal-bearing fluids through fractures. The result is a network of narrow, steeply dipping veins carrying copper as chalcopyrite, tin as cassiterite, and smaller amounts of tungsten, zinc and silver.
That has two consequences worth holding on to. First, the deposits are known. Generations of miners left behind shafts, levels, plans and sampling records, and modern exploration companies have been able to drill targets that were mapped out decades ago. Second, these are narrow-vein operations, not the vast open pits of Chile or Peru. Costs per tonne are higher, the mining method is selective, and the workforce needs real underground skill. That is the trade-off: known geology, harder economics.
South Crofty: the flagship
South Crofty, at Pool between Camborne and Redruth, is the project everyone in Cornish mining circles watches. It was the last working tin mine in Cornwall when it closed in 1998 and flooded, and it has changed hands more than once since. Its current owner has concentrated on the unglamorous groundwork: pumping out the flooded workings through the New Cook's Kitchen shaft, treating the mine water and discharging it, and drilling to confirm what the old records suggested.
Cornwall Council has granted the consents needed for underground working and surface infrastructure. Points of detail still matter, though. The mine sits within the Cornwall and West Devon Mining Landscape World Heritage Site, which raises the bar for surface design, traffic and visual impact, and any discharge to the Red River has to satisfy the Environment Agency.
Tin is the primary target, with copper and tungsten as credits. By world standards the planned output would be modest — far smaller than the giant copper mines that dominate global supply — but it would be the first new metal mine of its kind in the UK for years, and that alone makes it a test case.
What stands between a permit and ore
- Dewatering and water treatment: the mine has to stay dry, continuously, with discharge limits met every day.
- Shaft and decline access: refurbishment and safe access for people and equipment.
- Processing plant: built, commissioned and tuned to a specific orebody.
- Financing: capital for construction, usually the hardest item to close.
- People: recruiting and training underground crews after a long gap in Cornish metal mining.
- Offtake or marketing: someone willing to buy concentrate, and a route to a smelter.
The wider Cornish pipeline
South Crofty is not alone. Redmoor, in east Cornwall, is a tin-tungsten-copper deposit that has passed through several owners and some ambitious drilling campaigns. Cornish Lithium's work at United Downs and around Trelavour has focused on lithium but has generated a wealth of geological and hydrogeological data for the region. Historic sites such as Wheal Jane already host mine water treatment infrastructure, which is a reminder that water management is a permanent obligation, not a box ticked at planning stage.
Just over the border in Devon, the Drakelands tungsten operation at Hemerdon has had a turbulent history — a useful case study in how a technically sound project can still stumble on process plant performance and financing. And Imerys' china clay operations remain the largest extractive employer in the region, with the workforce, haulage and permitting experience that a new metal mine would lean on.
Permitting: layered, slow and local
Anyone imagining a single government approval is wide of the mark. A UK metal mine needs planning consent from the minerals planning authority — Cornwall Council in this case — plus an environmental permit from the Environment Agency covering mine water and waste, abstraction or impoundment licences where water is taken or stored, explosives licensing, and health and safety notifications. Heritage and ecological designations add further assessment.
The practical effect is that consenting is a sequence, not an event. Months of baseline monitoring usually precede an application. Statutory consultees each have their own questions. And the local planning committee, not a national body, makes the call — which is why community engagement in Camborne, Pool and Redruth matters as much as the drilling results.
Money and the critical minerals strategy
The UK's critical minerals strategy, first published in 2022 and refreshed since, is best understood as a signal rather than a subsidy. It shapes how government bodies such as the British Geological Survey's Critical Minerals Intelligence Centre assess risk, and it nudges public finance institutions — UK Export Finance among them — to look more seriously at projects that support supply security.
It does not grant a permit and it does not pay for a shaft. Junior mining companies still raise most of their money in equity markets that are thin for small, pre-production projects, so a Cornish mine is likely to need a partner, a royalty or streaming arrangement, or a strategic investor before construction. That is normal for the sector, but it is the step most likely to delay a timeline.
One sensible note for readers: mining shares are volatile and small-cap explorers can lose most of their value. Nothing here is investment advice, and anyone considering a position should take regulated professional advice first.
What it means for UK copper supply
Be realistic. Cornwall will not come close to covering UK copper demand, which is driven by wiring, motors, electronics, construction and the shift to electrified heating and transport. Even if South Crofty reaches production later this decade, its copper output would be measured in a few thousand tonnes a year at most — a rounding error against national consumption.
What it does offer is different: a domestic source of concentrate, proof that the UK can still permit and build a metal mine, and a trained workforce that future projects could draw on. In the near term, recycled copper and better recovery from waste electronics will do more for UK supply security than any single mine.
How to follow Cornish copper without the hype
If you want to track progress properly rather than react to headlines, a few habits help.
- Read the regulatory news filings, not the press releases. Financing terms and resource updates are where the substance sits.
- Check Cornwall Council's planning portal for committee dates and officer reports on any application in the Camborne and Redruth area.
- Watch Environment Agency consultation pages for permit variations covering water discharge.
- Follow dewatering milestones. If water levels are falling and treatment is compliant, a project is genuinely advancing.
- Look at technical reports and mineral resource statements rather than presentation slides, and note the date on every number.
- Keep an eye on tin and copper prices together. South Crofty's economics lean on tin, so copper headlines alone tell you only part of the story.
Cornwall's copper story is real, slow and unglamorous: pumps, permits, drills and paperwork. That is exactly what a working mine looks like before it produces anything.
Photo: Norrisskyia / Pixabay